Scale of Operations
Revenue
Description
Revenue represents the annual sales income generated by a company’s core operations, less sales adjustments such as granted discounts, value-added tax (VAT), and other direct taxes.
Interpretation
Revenue can be used to assess and compare the scale of business operations. However, when comparing revenue figures, the differing structures of companies and industries must be taken into account. Inflation affects revenue trends.
Value Added
Description
Value added represents the additional value a company creates for the products and services it purchases before the final product is delivered to the customer. This metric indicates how effectively a company utilizes its workforce and tangible capital.
Interpretation
The higher the figure, the more successfully the company has transformed raw materials—which are available to all suppliers—into something of value to the customer. For example, a specific employee can add significant value to a service through their own expertise.
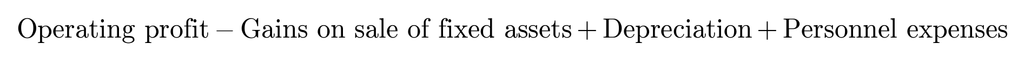
Billing
Description
In addition to net sales, this figure takes into account any prepayments received from customers. It aims to distribute the company’s sales more evenly across financial periods.
Interpretation
This figure allows for an assessment of the scale of the company’s business operations and facilitates comparisons with other companies. Billing is a more useful metric than net sales when comparing companies whose revenue may fluctuate significantly from year to year—such as those relying on one-off projects, for instance in the construction industry.
Revenue Growth Rate
(Revenue growth)
Description
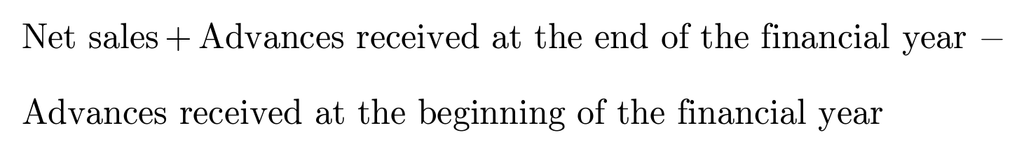
The revenue growth rate reflects the development of sales related to a company’s core operations over the previous financial year. It illustrates the expansion of business operations better than net profit does, as the figure is unaffected by accounting entries or changes in costs.
Interpretation
Growth in this metric typically stems from an expanded product or service portfolio, price increases, or successful sales of existing products. The growth rate should exceed the rate of real inflation; otherwise, no actual growth is taking place.
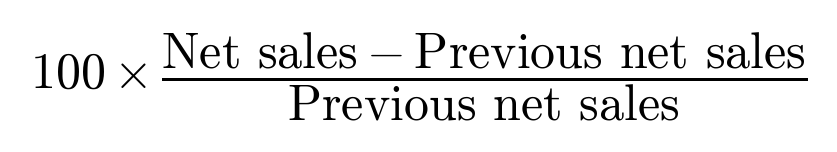
Value-added Margin
(Value-added margin)
Description
This ratio expresses value added as a proportion of the company’s net sales. Value added represents the value a company adds to the products and services it purchases before the final product is delivered to the customer. The ratio indicates how effectively the company utilizes its workforce and other capital.
Interpretation
Relating value added to the company’s sales volume makes this ratio more comparable across different companies.
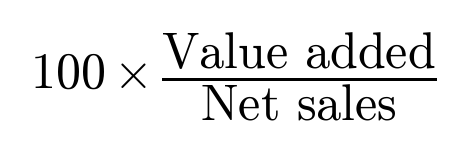
Balance Sheet Total
(Total assets)
Description
The balance sheet is divided into two parts: assets on one side, and the sum of equity and liabilities (debt) on the other. The balance sheet total indicates the amount of capital committed to the company at a specific point in time, thereby reflecting the scale of the business operations.
Interpretation
The balance sheet total reflects the scale of the company’s operations. As operations expand, the amount of committed capital increases. When comparing balance sheet totals, industry-specific characteristics must be taken into account: in capital-intensive sectors, such as manufacturing, the amount of committed capital is typically higher than in service companies that rely primarily on human labor.
Number of Personnel
(Number of personnel)
Description
The number of personnel indicates the average number of employees in the company during the financial year. Typically, only the number of full-time employees is taken into account. If a company employs a significant number of part-time workers, working hours can be aggregated and divided by the standard full-time workload.
Interpretation
Along with other metrics, the number of personnel reflects the scale of the company’s operations. When comparing companies, it is important to consider that they may utilize significant amounts of external labor. The Accounting Board has issued guidelines for calculating the average number of employees. According to these guidelines, the number of personnel for each month is summed up and divided by the number of months.