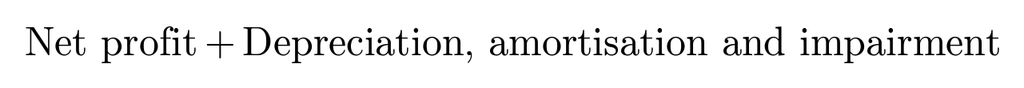
Liquidity
Quick Ratio
Description
The quick ratio measures liquidity at the time of the financial statements. Liquidity may fluctuate significantly during the financial year. Prepayments are deducted from current liabilities only to the extent that they relate to work already performed. It is also known as the “acid test.”
Interpretation
Excellent > 1.5; good 1–1.5; satisfactory 0.5–1; marginal 0.3–0.5; poor < 0.3.
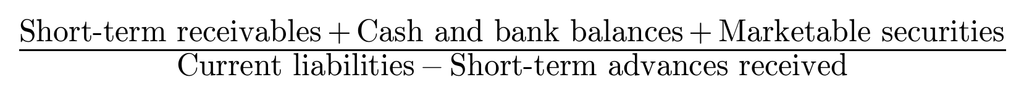
Current Ratio
Description
The current ratio is a liquidity metric that indicates the relationship between current assets and short-term liabilities.
Interpretation
Good > 2; satisfactory 1–2; poor < 1. An excessively high ratio may indicate inefficient use of the company’s cash resources.

Financial result
(Income before extraordinary items)
Description
The financial result reflects the company’s ability to repay loans and self-finance working capital and investments using the earnings generated from core operations and regular ancillary business activities.
Interpretation
The financial result should be positive. A negative financial result implies that loan repayments and investments must be financed through means other than internally generated funds.